Health Insurance vs Mediclaim: What’s the Difference and Which One Should You Choose in India?
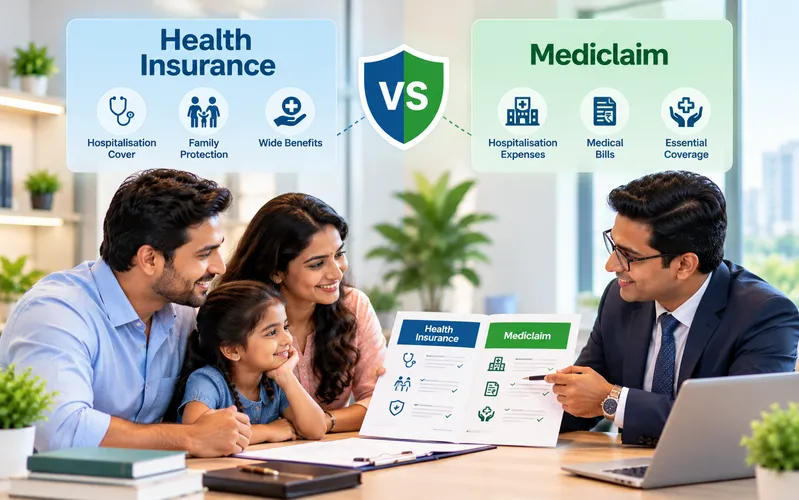
Are Health Insurance and Mediclaim really different, or are they two names for the same protection?
Many people in India use the terms Health Insurance and Mediclaim interchangeably. However, when comparing policies, they often come across differences in hospitalisation coverage, medical benefits, waiting periods and premium costs.
Understanding these differences is important before buying a policy for yourself, your parents or your family.
The most important thing to know is that Mediclaim is generally a commonly used name for hospitalisation-focused health insurance, not a separate regulatory category. Modern policies using either name may offer a wide range of benefits. What matters is the actual coverage provided by the insurer.
At Niraj Shinde – Insurance Expert, Mumbai, we help individuals and families understand medical insurance plans, policy benefits, exclusions and coverage requirements.
1. What Is Mediclaim Insurance?
Mediclaim Insurance generally refers to a health insurance policy that helps cover eligible hospitalisation expenses arising from illness or accidental injury.
Depending on the policy, it may cover:
Hospital room and ICU charges
Doctor and surgeon fees
Operation and treatment expenses
Prescribed medicines during hospitalisation
Eligible day-care procedures
Pre- and post-hospitalisation medical expenses
Mediclaim policies usually work on an indemnity basis, meaning the insurer pays eligible medical expenses up to the available sum insured, subject to policy conditions.
Example: If you have a Mediclaim policy with a sum insured of ₹5 lakh and incur an eligible hospital bill of ₹2 lakh, the insurer may pay the admissible amount through cashless treatment or reimbursement. Deductibles, co-payments and exclusions can affect the final amount.
2. What Is Health Insurance?
Health Insurance is the broader category of insurance that protects against specified healthcare-related financial risks.
It can include hospitalisation policies, family floater plans, top-up plans and benefit-based products such as certain critical illness policies.
Depending on the insurer and selected plan, Health Insurance may provide:
Hospitalisation and surgery coverage
Day-care procedures
Pre- and post-hospitalisation expenses
Emergency ambulance benefits
AYUSH treatment
Maternity and newborn coverage
Outpatient consultation benefits
Organ donor expenses
Restoration of the sum insured
Critical illness benefits under applicable policies
Not every Health Insurance policy includes all these features. Some benefits are optional or subject to specific conditions.
The key is to select coverage based on your healthcare requirements rather than relying only on the policy name.
3. Health Insurance vs Mediclaim – Key Differences
The table below explains how traditional hospitalisation-focused Mediclaim plans are often compared with broader Health Insurance products.
| Feature | Traditional Mediclaim | Broader Health Insurance |
|---|---|---|
| Main purpose | Hospitalisation expenses | Various medical and health-related risks |
| Hospitalisation | Usually included | Commonly included in indemnity plans |
| Pre- and post-hospitalisation | Depends on policy | Available in many plans |
| Day-care treatment | Depends on policy | Available in many plans |
| OPD benefits | May be limited or optional | Available in selected plans |
| Maternity benefits | Depends on policy | Available in selected plans |
| Family coverage | May be available | Individual and family options |
| Premium | Depends on benefits and risk | Depends on benefits and risk |
| Claims | Usually actual eligible expenses | Indemnity or fixed-benefit, depending on product |
Important: These are common product-design differences, not universal rules. A policy called Mediclaim may provide broad benefits, while a policy called Health Insurance may have limited coverage.
4. What Is the Difference Between Cashless and Reimbursement Claims?
Both Health Insurance and Mediclaim policies may provide cashless and reimbursement claim facilities.
Cashless Health Insurance Claim
At an eligible network hospital, the insurer or Third-Party Administrator (TPA) reviews the hospital’s pre-authorisation request.
If approved, admissible expenses are settled according to the policy and hospital arrangement. The policyholder remains responsible for non-payable expenses, deductibles and any applicable co-payment.
Reimbursement Health Insurance Claim
In a reimbursement claim, the policyholder pays the hospital expenses and submits the required documents to the insurer.
The insurer reviews the claim and reimburses eligible expenses according to the policy.
Tip: Before purchasing a policy, check the insurer’s hospital network, cashless procedures and reimbursement documentation requirements.
5. Which Is Better for Families in India?
Families should focus on the level of medical protection offered rather than deciding between the words Mediclaim and Health Insurance.
When choosing a family policy, consider:
Family Floater Sum Insured: Ensure the shared coverage is suitable for the number and ages of insured members.
Room Rent Conditions: Check whether room category restrictions or proportionate deductions can apply.
Waiting Periods: Review waiting periods for pre-existing diseases and specified treatments.
Restoration Benefits: Understand when and how the sum insured can be restored after eligible claims.
Hospital Network: Check relevant network hospitals near your home and workplace.
Co-Payment: Understand whether a percentage of admissible expenses must be paid by the policyholder.
Maternity and Newborn Benefits: Check availability if you are planning to start or expand your family.
For many families, a suitable base Health Insurance policy combined with an eligible Super Top-Up policy may be worth evaluating for additional medical expense protection.
6. How Much Health Insurance Coverage Do You Need in Mumbai?
Healthcare expenses can vary significantly depending on the hospital, treatment and medical condition.
People living in Mumbai, including Dadar, Prabhadevi, Lower Parel, Worli, Matunga, Mahim and surrounding areas, should consider the possible cost of treatment at hospitals they would realistically use.
When deciding on the sum insured, review:
Age and number of family members
Existing employer medical coverage
Current medical conditions and future needs
Preferred hospital and room category
Emergency savings
Policy exclusions and deductibles
Budget for insurance premiums
Top-Up and Super Top-Up options
There is no single coverage amount suitable for everyone. Choose the sum insured after assessing your financial circumstances and likely healthcare costs.
7. Five Mistakes to Avoid When Buying Health Insurance
Mistake 1 — Choosing the Cheapest Premium
A lower premium may come with restrictions, co-payments, deductibles or limited benefits.
Mistake 2 — Ignoring Waiting Periods
Some conditions may have waiting periods before coverage becomes available. Review the exact policy wording.
Mistake 3 — Not Checking Room Rent Limits
Room rent restrictions can affect eligible claim payments in some policies.
Mistake 4 — Depending Only on Employer Insurance
Employer-provided medical coverage may end when you leave your organisation. Individual insurance can provide separate protection, subject to its terms.
Mistake 5 — Not Disclosing Medical Information
Provide accurate medical and other information requested by the insurer. Material misrepresentation or non-disclosure may affect policy or claim outcomes under applicable rules.
How to Choose the Right Insurance Policy in India
Buying insurance should not be based only on the lowest premium.
Before choosing a policy, consider these five important factors:
1. Understand Your Financial Risks
Identify which unexpected events could affect your family, income, property or business.
2. Select Suitable Coverage
Review the sum insured, policy limits and benefits based on your financial responsibilities.
3. Compare Policies Carefully
Check premiums, deductibles, exclusions, waiting periods and other important conditions.
4. Understand the Claim Process
Review how claims are reported, which documents are required and how insurer assistance works.
5. Review Your Insurance Regularly
Life changes, medical needs, vehicle values and business operations may change over time. Review your existing coverage when your circumstances change and before renewal.
8. Can You Have Both Mediclaim and Health Insurance?
Yes. You can hold more than one health insurance policy, including individual and employer-sponsored coverage.
For example, you may have an employer Group Mediclaim policy and a separate personal Health Insurance policy.
Having multiple policies can help provide additional eligible coverage, but you cannot recover more than the admissible medical expenses under indemnity policies for the same loss.
The insurer’s applicable claims procedures and coordination requirements should be followed.
9. How to Choose the Right Health Insurance Plan in India
Before buying medical insurance, follow these five steps:
Step 1 – Identify Your Healthcare Needs
Consider your age, family size, existing health coverage and financial responsibilities.
Step 2 – Compare Actual Benefits
Review hospitalisation, pre- and post-hospitalisation expenses, day-care treatments, restoration and optional benefits.
Step 3 – Check Exclusions and Waiting Periods
Understand what the insurer does not cover and when particular benefits become available.
Step 4 – Review Claims Services
Check hospital networks, reimbursement requirements, cashless facilities and insurer support.
Step 5 – Select Suitable Coverage
Choose a policy based on your healthcare requirements, financial capacity and the policy’s terms rather than only its premium or product name.
10. Why Choose Niraj Shinde – Insurance Expert in Mumbai?
Understanding medical insurance can be confusing when policies contain technical terms, different benefits and exclusions.
At Niraj Shinde – Insurance Expert, we focus on helping individuals, families and working professionals understand available insurance solutions.
We provide guidance on:
Individual Health Insurance
Family Health Insurance
Mediclaim Coverage
Health Insurance Policy Renewals
Group Health Insurance
Claims Procedures and Documentation
Our goal is to help customers understand insurance protection clearly before making important financial decisions.
Frequently Asked Questions About Health Insurance vs Mediclaim
-
1. Is Mediclaim the Same as Health Insurance?Mediclaim is commonly used to refer to hospitalisation-focused health insurance in India. It is not a completely separate regulatory category. The actual coverage depends on the policy.
-
2. Which Is Better: Mediclaim or Health Insurance?Neither name is automatically better. Compare the sum insured, hospitalisation benefits, waiting periods, exclusions, co-payments and optional features before choosing.
-
3. Does Mediclaim Cover Surgery?Eligible hospitalisation and surgical expenses may be covered under a Mediclaim policy, subject to policy limits, waiting periods and exclusions.
-
4. Does Health Insurance Cover OPD Expenses?Some policies provide OPD benefits, including eligible consultations and diagnostics. OPD coverage is not automatically included in every health insurance policy.
-
5. Can I Buy Health Insurance for My Parents?Yes. Insurers offer medical insurance options for eligible parents and senior citizens. Premiums, co-payments, waiting periods and benefits depend on the selected policy.
-
6. Is Employer Mediclaim Enough?Employer Mediclaim can be useful, but coverage may end when employment ends. Additional individual coverage may be appropriate depending on your needs.
-
7. Can I Port My Existing Health Insurance Policy?Eligible health insurance policies may be portable according to applicable IRDAI and insurer requirements. Continuity benefits, underwriting and portability conditions should be reviewed before changing insurers.
-
8. Where Can I Get Health Insurance Guidance in Dadar, Mumbai?Contact Niraj Shinde – Insurance Expert for information about Health Insurance, Mediclaim, Family Health Insurance, renewals and available policy options.
Looking for Health Insurance in Mumbai?
Protecting yourself and your family starts with understanding your insurance options.
Whether you are purchasing medical insurance for the first time or reviewing an existing policy, we can help you understand coverage benefits, exclusions, premiums and renewal requirements.
Contact Niraj Shinde – Insurance Expert
Phone: +91 89760 78348
Email: info@nirajishindeinsurance.com
Location: Prabhadevi, Mumbai, Maharashtra – 400025