Loading...

Developing personalized charity journeys to increase donor satisfaction strengthen community trust and expand our humanitarian by global philanthropic.

Bike Insurance

Bike Insurance Plans for a Safer and Worry-Free Ride

Your two-wheeler is an important part of your everyday journey. Protect it against unexpected accidents, theft, fire and natural disasters with suitable Bike Insurance coverage.

Explore Third-Party, Comprehensive and Own-Damage Bike Insurance options for motorcycles and scooters with personalised guidance from Niraj Shinde – Insurance Expert in Mumbai.

Bike Insurance

What Is Bike Insurance?

Bike Insurance, also known as Two-Wheeler Insurance, provides financial protection against covered risks involving your motorcycle or scooter, including accidents, theft, fire and third-party liabilities, depending on the policy.
In India, valid Third-Party Insurance is mandatory for two-wheelers used on public roads. It covers eligible legal liabilities arising from injury, death or property damage caused to a third party.
For broader protection, Comprehensive Bike Insurance also covers eligible damage to your own vehicle. Optional add-ons such as Zero Depreciation, Engine Protection and Roadside Assistance may provide additional benefits, depending on the plan.
At Niraj Shinde – Insurance Expert, Mumbai, we help bike owners understand insurance plans, coverage benefits, exclusions and renewal options to choose suitable protection for their two-wheelers.

Bike Insurance Coverage: What's Included and What's Not?

✅  What Bike Insurance May Cover

❌  What Project Insurance Generally Does Not Cover

Benefits of Project Insurance

Financial Protection for Construction Works

Project Insurance can help manage eligible repair or reconstruction expenses following covered damage to insured works during construction.

Plant and Machinery Installation Protection

EAR Insurance provides protection against specified accidental damage to eligible machinery and equipment during erection, installation and testing.

Coverage Against Fire and Natural Disasters

Selected policies cover specified project damage caused by fire, storms, floods, earthquakes and other insured incidents.

Protection for Project Materials and Equipment

Eligible policies protect declared construction materials, temporary works and specified site equipment against covered physical damage.

Third-Party Liability Protection

Applicable liability sections can help address specified legal claims involving injury or property damage to third parties arising from project activities.

Support for Project Risk Management

Suitable Project Insurance helps developers, contractors and engineering companies manage eligible financial losses that may affect construction or installation activities.

Types of Project Insurance Plans

Explore Insurance Options for Construction and Engineering Projects

Different projects involve different activities, timelines and risk exposures. Choosing suitable Project Insurance depends on the nature of work, project value and contractual requirements.

Contractors' All Risks (CAR) Insurance

CAR Insurance is designed for eligible civil construction projects such as residential and commercial buildings, roads, bridges, pipelines and other infrastructure works. It provides specified physical damage and third-party liability protection.

Erection All Risks (EAR) Insurance

EAR Insurance covers specified risks during the installation, erection, testing and commissioning of eligible plant, machinery and industrial equipment. It is relevant for engineering and industrial installation projects.

Single Project Insurance Policy

A Single Project Insurance Policy provides coverage for one defined construction or engineering project during the agreed policy period. The project owner, contractor and other parties may be insured as specified in the policy.

Annual Contractors' Insurance

Certain insurance arrangements can cover multiple eligible smaller projects undertaken by a contractor during an agreed period, subject to declaration requirements, project limits and insurer conditions.

Project Insurance with Additional Covers

Eligible CAR or EAR policies may offer extensions for surrounding property, debris removal, maintenance risks, off-site storage, transit or certain delay-related losses, subject to availability and policy terms.

img Process

How to Choose the Right Bike Insurance Plan
Bike Insurance Plan

01

Understand Your Coverage Needs

Consider your bike’s age, model, market value, daily usage and parking conditions. Decide whether basic third-party protection is sufficient or broader own-damage coverage is suitable.

02

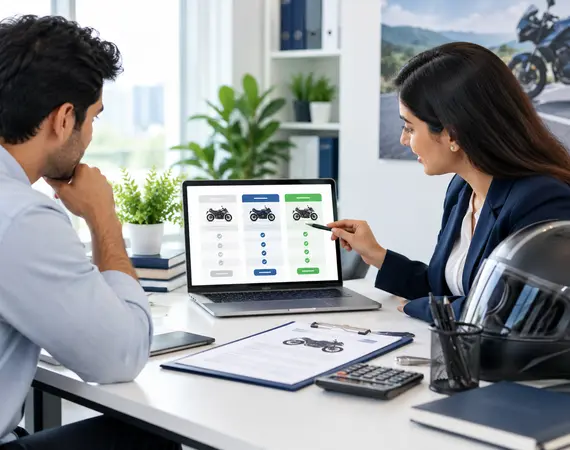
Compare Bike Insurance Plans

Compare available policies based on premiums, Insured Declared Value (IDV), deductibles, exclusions, garage networks and included benefits. Look beyond the cheapest premium.

03

Check Claim Services and Insurer Support

Review the insurer’s claim procedures, cashless garage availability, repair assessment process and required documentation before choosing a policy.

04

Select Useful Add-On Covers

Explore Zero Depreciation, Engine Protection, Roadside Assistance and other available add-ons based on your two-wheeler’s age, usage and insurance budget.

0 +

Families Supported

0 +

Insurance Partners

0 %

Client Support

Who Needs Bike Insurance?

Bike Insurance is important for every motorcycle and scooter owner in India. Whether you use your two-wheeler for daily office travel, college, business visits or personal transportation, valid third-party insurance is legally required when riding on public roads.

Comprehensive Bike Insurance can be especially useful for people who own new or expensive motorcycles, regularly travel through heavy traffic, park in open areas or live in regions affected by heavy rainfall and flooding.

Working professionals, students, families and self-employed individuals can benefit from understanding their insurance needs and choosing appropriate protection. Two-wheelers used for commercial delivery or business activities may require suitable commercial-use coverage rather than a standard private policy.

At Niraj Shinde – Insurance Expert, Mumbai, we provide guidance on Bike Insurance, policy renewals, coverage options and claims-related procedures.

+91 89760 78348

info@nirajishindeinsurance.com

What Affects Your Bike Insurance Premium?

How the Bike Insurance Claim Process Works

Inform the Insurance Company

Notify your insurer promptly after an accident, theft or other covered incident. Share the relevant details and follow the claim notification timelines mentioned in your policy.

Collect Required Documents

Keep your vehicle registration certificate (RC), driving licence, insurance policy, photographs of the damage and other documents requested by the insurer. A police report or FIR may be required for theft and certain accidents.

Vehicle Inspection and Repair

For own-damage claims, the insurer may arrange an assessment of the damage. Depending on your policy and garage availability, eligible repairs may be processed through cashless or reimbursement arrangements.

Claim Assessment and Settlement

The insurance company reviews the claim, supporting documents and policy conditions. Approved claims are settled according to the applicable coverage, deductibles, depreciation and other policy terms.

Common Questions About Bike Insurance in India

  • 1. Is Bike Insurance mandatory in India?
    Yes. Every motorcycle and scooter used on public roads in India must have at least valid Third-Party Insurance under the Motor Vehicles Act. It provides coverage for specified legal liabilities involving third parties. Own-damage insurance is optional but offers additional protection for your vehicle.
  • 2. What is the difference between Third-Party and Comprehensive Bike Insurance?
    Third-Party Bike Insurance covers specified legal liabilities arising from injury, death or property damage to others. Comprehensive Bike Insurance includes third-party liability and own-damage protection for covered accidents, theft, fire and natural disasters.
  • 3. How much does Bike Insurance cost in India?
    Bike Insurance premiums depend on the type of coverage, engine capacity, vehicle age, IDV, applicable discounts and optional add-ons. Third-party premiums follow prescribed rates, while own-damage premiums vary by insurer and vehicle-related factors.
  • 4. Can I renew my Bike Insurance online?
    Yes. Bike Insurance can generally be renewed online through authorised insurer websites or distribution channels. You may need your vehicle registration number, previous policy details and other information requested by the insurer. An expired policy may require additional checks or inspection.
  • 5. What is Zero Depreciation Cover in Bike Insurance?
    Zero Depreciation is an optional add-on that reduces or removes specified depreciation deductions on eligible replacement parts during an own-damage claim. Coverage limits, excluded parts, claim limits and availability vary by insurer.
  • 6. Does Bike Insurance cover theft?
    Theft of the insured motorcycle or scooter is generally covered under eligible Comprehensive or Standalone Own-Damage Insurance policies. Third-party insurance alone does not cover theft of your own vehicle.

Niraj Shinde Insurance & Financial Services offers trusted insurance guidance in Dadar, Prabhadevi and Mumbai, helping individuals and businesses with policy selection, renewals and claim assistance.

Contact

Phone & Email

info@nirajishindeinsurance.com
+91 89760 78348

Office Address:

Shop no. 8, Raj chs, opp. marathe udyog, Century Bazaar, Prabhadevi, Mumbai, Maharashtra 400025

© 2026 Niraj Shinde. Designed & Developed by Peaceinfotech Services Pvt. Ltd.

Policy & privacy / Terms & conditions